Original Medicare pays for a lot, but not everything. A Medicare Supplement plan, also called Medigap, helps pay the rest. For 35 years, DGS Benefits has helped New Jersey residents sort out their Medicare options in plain English and without pressure.
What is a Medicare Supplement plan?
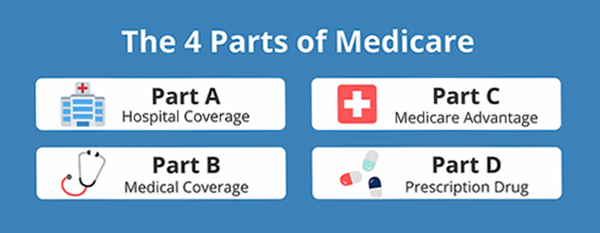
Original Medicare (Part A and Part B) covers hospital and medical care, but you still pay deductibles, coinsurance, and copayments. There is also no limit on what you could owe in a year with a serious illness. A Medicare Supplement plan, sold by private insurance companies, helps cover many of those gaps.
The plans are standardized and labeled with letters. A given lettered plan covers the same basic benefits no matter which company sells it. What changes from company to company is the price and the service behind it. Two things to know up front: Medicare Supplement plans do not include prescription drug coverage, and they work only alongside Original Medicare, not with a Medicare Advantage plan.
Which Medicare Supplement plans can you buy in New Jersey?
Which letters are open to you depends partly on when you became eligible for Medicare. If you became eligible on or after January 1, 2020, federal law does not allow Plans C and F. In New Jersey, carriers offer Plans D and G instead. They cover the same benefits as C and F, except that you pay the Medicare Part B deductible yourself ($283 in 2026). If you became eligible before 2020, more plans may be available to you. We will show you exactly which plans and companies fit your situation.
Who is eligible?
You can buy a Medicare Supplement plan if you have both Part A and Part B. Most people qualify when they turn 65. In New Jersey, some people under 65 who are on Medicare because of a disability can also get certain plans, and the rules depend on your age. Call us and we will check your exact situation.
When should you enroll?
Your best window is the six-month Medigap Open Enrollment Period. It starts the month you are 65 or older and enrolled in Part B. During that window, an insurer cannot turn you down or charge you more because of your health. Miss it, and the company may ask health questions and can decline your application, although some situations, such as losing other coverage, come with their own protections. That is why we like to talk with people two to three months before they turn 65.
What does it cost?
There are two separate costs, and people often confuse them.
Medicare's own costs. In 2026, the standard Part B premium is $202.90 a month and the Part B deductible is $283 a year. The Part A hospital deductible is $1,736 per benefit period. Part A is premium-free for most people with enough work history. These are set by the government and are the same no matter who you buy a supplement from. Medicare announces the numbers for the next year each fall.
Your Medicare Supplement premium. This is paid to the insurance company and is separate from your Medicare premiums. It varies by plan letter, by company, and by your age, and it can rise over time. We compare quotes from a number of carriers side by side so you can see the real difference.
Medicare Supplement or Medicare Advantage?
This is the biggest decision most people face at 65. A Medicare Supplement plan works with any doctor or hospital in the country that accepts Medicare, with no network and no referrals, and it usually means a higher monthly premium with fewer surprise bills. Medicare Advantage replaces Original Medicare with a private plan, often with a lower premium but with networks and copays. Neither is right for everyone. We will walk you through both. Already on Medicare Advantage or Part D? See what can change each fall in Medicare Open Enrollment in NJ: What Changes Every Year.
What Medicare and Medigap do not cover
Neither Original Medicare nor a Medicare Supplement plan pays for long-term custodial care, such as help with bathing, dressing, or daily living. If that worries you, read about long-term care insurance in NJ. To protect your family, see life insurance and final expense insurance.
Frequently asked questions
Can I keep my doctors?
Yes. A Medicare Supplement plan works with any provider in the United States who accepts Medicare.
Does a Medicare Supplement plan cover my prescriptions?
No. Drug coverage comes from a separate Medicare Part D plan, and we can help you choose one.
Can I switch plans later?
Yes, you can apply to change at any time. Outside your open enrollment window or another guaranteed situation, though, the new company may ask health questions and can say no. Talk to us before you cancel anything.
Can I have a Medicare Supplement plan and a Medicare Advantage plan?
No. You use one or the other.
I am under 65 and on Medicare. Can I still get a Supplement?
Often, yes. New Jersey has special rules that guarantee access to certain plans for people on Medicare because of a disability. Which plan and which company depend on your age, so call us. If you are still waiting for Medicare, see our page on SSDI and Social Security disability help.
Is a consultation really free?
Yes. Your first consultation is free. Contact us to get started.
DGS Benefits Inc. is a licensed insurance broker and is not affiliated with or endorsed by the U.S. government or the federal Medicare program. We do not offer every plan available in your area.
Please contact Medicare.gov, 1-800-MEDICARE or the New Jersey State Health Insurance Assistance Program at 1-800-792-8820 for information on all of your options.
Medicare Supplement plans are sold by private insurance companies, and premiums, availability, and eligibility rules vary.